
- Tax Credit vs Tax Deduction: What’s Actually the Difference? - October 20, 2026
- Is AFC Scholarship Fund Legit? What Donors Should Know About Its Backing and Compliance - September 25, 2026
“Credit” and “deduction” get used almost interchangeably in casual conversation, but they work in completely different ways, and mixing them can lead you to badly overestimate or underestimate what a tax benefit is actually worth. Here’s the plain language breakdown of each, a side-by-side example using the same dollar amount, and a real-world credit that’s about to make this distinction matter for a lot of everyday donors.
What Is a Tax Deduction?
A tax deduction reduces your taxable income before your tax bill is calculated. It doesn’t come off what you owe directly. Instead, it shrinks the income the IRS uses to figure out how much you owe in the first place.
A deduction’s value depends entirely on your marginal tax bracket. If you’re in the 24 percent bracket, a $1,000 deduction saves you roughly $240. If you are in the 12 percent bracket, that same $1,000 only saves you about $120. The deduction amount stays the same, but its actual dollar value to you moves depending on your income and bracket.
There’s also a practical hurdle with many deductions: you generally have to itemize to claim them, and the standard deduction is high enough that most taxpayers don’t. Charitable giving has changed on this point. Starting with the 2026 tax year, taxpayers who take the standard deduction can still deduct up to $1,000 in cash gifts to eligible charities, or up to $2,000 for married couples filing jointly, according to the IRS. Taxpayers who do itemize face a new floor, where only giving above 0.5 percent of adjusted gross income is deductible, and the tax benefit for those in the top bracket is capped at 35 cents on the dollar. So the charitable deduction reaches more people than it used to, but it is still modest and still depends on your situation.
What Is a Tax Credit?
A tax credit works differently, and more directly. Instead of reducing your taxable income, it reduces what you actually owe, dollar for dollar, after your tax bill has already been calculated.
This is the detail that confuses people the most: a tax credit’s value doesn’t depend on your tax bracket at all. A $1,000 credit is worth exactly $1,000 off your tax bill whether you’re in the 12 percent bracket or the 37 percent bracket. That flat, bracket-independent value is what makes credits substantially more powerful than deductions of the same size.
Credits also come in two types worth knowing about. A refundable credit can reduce your tax bill below zero, with the difference paid to you as a refund. A nonrefundable credit can only reduce your bill down to zero. If the credit is worth more than you owe, the excess isn’t paid out as cash, though some nonrefundable credits allow you to carry the unused portion forward to future tax years rather than losing it outright.
This refundable-versus-nonrefundable split matters just as much as the credit-versus-deduction split. The Earned Income Tax Credit, for example, is refundable, meaning a qualifying taxpayer can receive money back even if it exceeds what they owed. The Child Tax Credit is partially refundable, with a portion available as a refund and a portion capped at reducing your bill to zero. Plenty of other credits, including the one discussed later in this article, are fully nonrefundable, which caps the benefit at whatever you actually owe for the year, unless a carryforward provision applies.
A Side-by-Side Example
Numbers make this easier to see than definitions alone. Say you’re a married couple filing jointly, and each of you plans to give $1,700 to a charitable cause, for $3,400 in total. You’re comparing what happens if that gift qualifies for a credit versus a deduction.
As a credit: If you owe $4,000 in federal taxes before the credit, and each spouse’s $1,700 gift earns a $1,700 credit, a combined $3,400 comes off what you owe. Your bill drops straight to $600, no bracket math involved.
As a deduction: If that same $3,400 is only deductible, and you’re in the 24 percent tax bracket, the deduction saves you roughly $816. Your $4,000 tax bill would drop to about $3,184, not $600.
Same dollar amount given. Roughly four times the tax benefit under the credit structure compared to the deduction structure at a 24 percent bracket. That gap is the entire reason it’s worth knowing which one you’re dealing with before you assume you understand what a tax benefit is actually worth. (The $816 figure is the simplified textbook case. Starting in 2026, itemizers can only deduct giving above 0.5 percent of their adjusted gross income, which can shrink the deduction further.)
If you’re a single filer, cut every figure in half: a $1,700 gift, a $1,700 credit, and roughly $408 of deduction value in the 24 percent bracket. The ratio stays the same.
Same Gift, Different Taxpayers
The side-by-side above assumes a 24 percent bracket, but a deduction’s value changes with every taxpayer who claims it. Here’s what that same $3,400 gift from a married couple filing jointly looks like across a few different situations, assuming each couple owes at least that much in federal tax.
| Taxpayer situation (married, filing jointly) | Value as a deduction | Value as a credit |
| Takes the standard deduction (12% bracket) | About $240, since the non-itemizer deduction tops out at $2,000 | $3,400 |
| Itemizes, 12% bracket | About $408 | $3,400 |
| Itemizes, 24% bracket | About $816 | $3,400 |
| Itemizes, 35% bracket | About $1,190 | $3,400 |
Two things stand out. First, the deduction column ranges from about $240 to nearly $1,200 depending on who’s claiming it, while the credit column doesn’t move. Second, the first row is where most everyday donors land: a couple who takes the standard deduction can deduct only the first $2,000 of cash giving, no matter how much more they give. A credit isn’t capped that way or tied to itemizing, so that couple’s benefit is the same as anyone else’s, up to the credit’s limit. The itemizer rows are before the new 0.5 percent of income floor, which can reduce them further. For a single filer, cut every figure in half.
One caveat keeps this honest. A nonrefundable credit can only offset what you actually owe. A couple with $1,800 in federal tax liability couldn’t use the full $3,400 in a single year, though the unused $1,600 can generally be carried forward for up to five years rather than disappearing. That’s the one place where a credit’s benefit depends on your own tax picture, and it’s why checking your expected liability matters before you assume a credit’s full face value will land in a single filing.
A Real-World Example: The Education Freedom Tax Credit
Most tax credits people are familiar with are things you personally qualify for based on your own life circumstances, such as a child tax credit or an education credit for your own tuition. The Education Freedom Tax Credit (EFTC) works differently, and it’s a useful real-world example precisely because it makes the credit mechanism so explicit.
Starting January 1, 2027, a taxpayer who makes a qualifying cash contribution to a qualified Scholarship Granting Organization (SGO) like AFC Scholarship Fund can claim a nonrefundable, dollar-for-dollar federal tax credit of up to $1,700 per person, or up to $3,400 for married couples filing jointly, according to the IRS. Treasury’s proposed rules treat spouses on a joint return as separate taxpayers, each with their own $1,700 limit, so the $3,400 applies when each spouse makes and designates their own $1,700 gift.
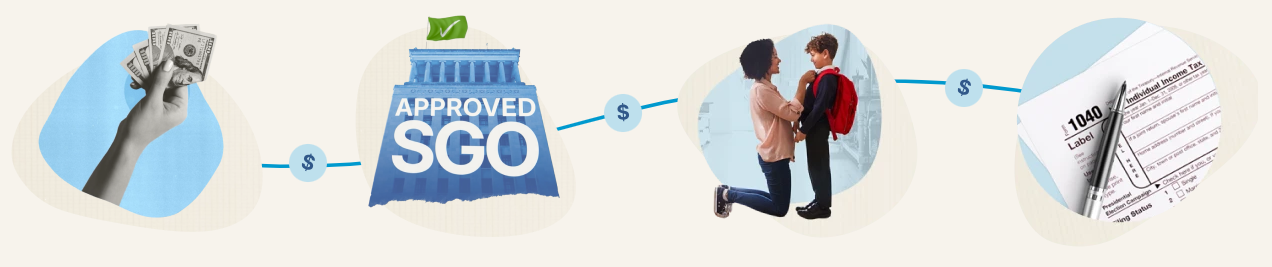
The sequence matters here, and it is worth explaining clearly. First you give, and the credit itself is something you claim later, when you file. It is never an instant discount or a real-time offset against your gift. The SGO then sends you a written acknowledgment, including a unique donor number, by January 31 of the following year, and the credit shows up on your federal return for the year.
This is a different structure than the charitable deduction most donors are used to. A regular charitable gift, deducted under the usual rules, is either capped at 1,000(2,000 for couples) if you don’t itemize or subject to the new 0.5 percent of income floor if you do, and its value shrinks or grows depending on your bracket, exactly like in the illustration above. The EFTC instead gives every qualifying donor the same flat, dollar-for-dollar benefit, up to $1,700 per person, or up to $3,400 for married couples filing jointly, regardless of their bracket. And a dollar claimed under this credit can’t also be separately deducted as a charitable contribution. It’s one benefit per dollar given, not both.
The requirement to actually generate this credit is given to a qualified SGO in a state that has opted into the tax credit. As of the IRS’s most recent update, 30 states have opted in. On the eligibility side, approximately 90 percent of American K-12 students are expected to qualify to receive a scholarship, which is a separate question from who can claim the credit as a donor. Any taxpayer may be able to claim the credit by giving to a qualified SGO, regardless of their own income.
SGO Example: AFC Scholarship Fund
AFC Scholarship Fund is a national scholarship network built to operate as a qualified SGO under the EFTC. It’s designed to give donors choice in where a contribution goes. They have multiple scholarship funds available, handle the compliance work behind the scenes, verify student eligibility, track the federally required 90/10 allocation between scholarships and administration, as well as issue the documentation a donor needs at filing.
It’s built on infrastructure from Odyssey network, which has moved more than $3 billion in scholarships and served over 157,000 students across 12 states. So the organization isn’t starting from zero on the operational side of running a scholarship program at scale.
When the donor portal launches, giving through AFC Scholarship Fund is designed to walk a donor through this process clearly: contribute to a qualified fund, receive the documentation needed for tax purposes, and claim the credit when filing, without needing to become a tax expert to understand what’s happening at each step.
Why The Credit vs. Deduction Distinction Matters Beyond the EFTC
Even outside of this specific credit, understanding the credit versus deduction difference changes how you should think about any tax benefit you’re offered, in any context. Financial advice, marketing materials, and even well-meaning friends often use “tax break” as a catch-all term that blurs the two together. Before assuming a benefit is worth what it sounds like, you should ask yourself a simple question. Does this reduce what I owe directly, or does it just reduce the income my tax bill gets calculated from?
That single question determines whether a benefit’s value is fixed, like a credit, or dependent on your personal tax bracket and itemizing status, like a deduction. Getting that distinction right is the difference between accurately estimating your own tax picture and being surprised at filing time.
Common Questions
Is a tax credit always better than a deduction of the same size? In almost every practical case, yes. A credit’s flat, dollar-for-dollar value beats a deduction’s bracket-dependent value unless someone is in an unusually high bracket and the deduction amount is very large relative to the credit being compared.
How does the EFTC work for married couples? Under Treasury’s proposed rules, spouses who file jointly are treated as two separate taxpayers, each with their own $1,700 limit, so a couple can claim up to $3,400. The full amount applies when each spouse makes and designates their own $1,700 gift. A single gift attributed entirely to one spouse shouldn’t be assumed to earn $3,400 on its own, so couples may want to confirm how their gifts are credited once final rules are published.
Can I get both a deduction and a credit for the same donation? No, at least not for the EFTC specifically. A dollar claimed as this credit can’t also be deducted as a charitable contribution. It’s one benefit per dollar given.
Do I need to itemize to claim the EFTC? No. The EFTC is a credit claimed directly on your federal return, so it doesn’t require itemizing the way many deductions do.
What happens if the credit is worth more than I owe? Because the EFTC is nonrefundable, it can reduce your tax bill to zero but won’t generate a refund beyond that. Any unused portion can generally be carried forward for up to five years.
Do I need to keep records of my donation? Yes. It’s good practice to retain your donation acknowledgment for at least three years, which lines up with the standard IRS audit window, regardless of whether you’re claiming a credit or a deduction.
For a deeper look at how Scholarship Granting Organizations themselves work, including the 90/10 rule that governs how they allocate funds, AFC’s SGO explainer is a good next stop once the credit-versus-deduction mechanics here make sense.
The Bottom Line
A deduction shrinks your taxable income, and its value rises and falls with your tax bracket. A credit reduces what you owe directly, dollar for dollar, regardless of bracket, which is why a $1,700 credit and a deduction of the same size can produce wildly different outcomes on the exact same gift. The Education Freedom Tax Credit is a clear, concrete example of the credit side of that equation, offering qualifying donors a flat, dollar-for-dollar benefit of up to $1,700 per person, or up to $3,400 for married couples filing jointly, when they give to a qualified SGO like AFC Scholarship Fund. Understanding which structure you’re working with before you give is the difference between guessing at your tax outcome and knowing it.